Hit by an Uninsured Driver on Your Motorcycle in North Carolina
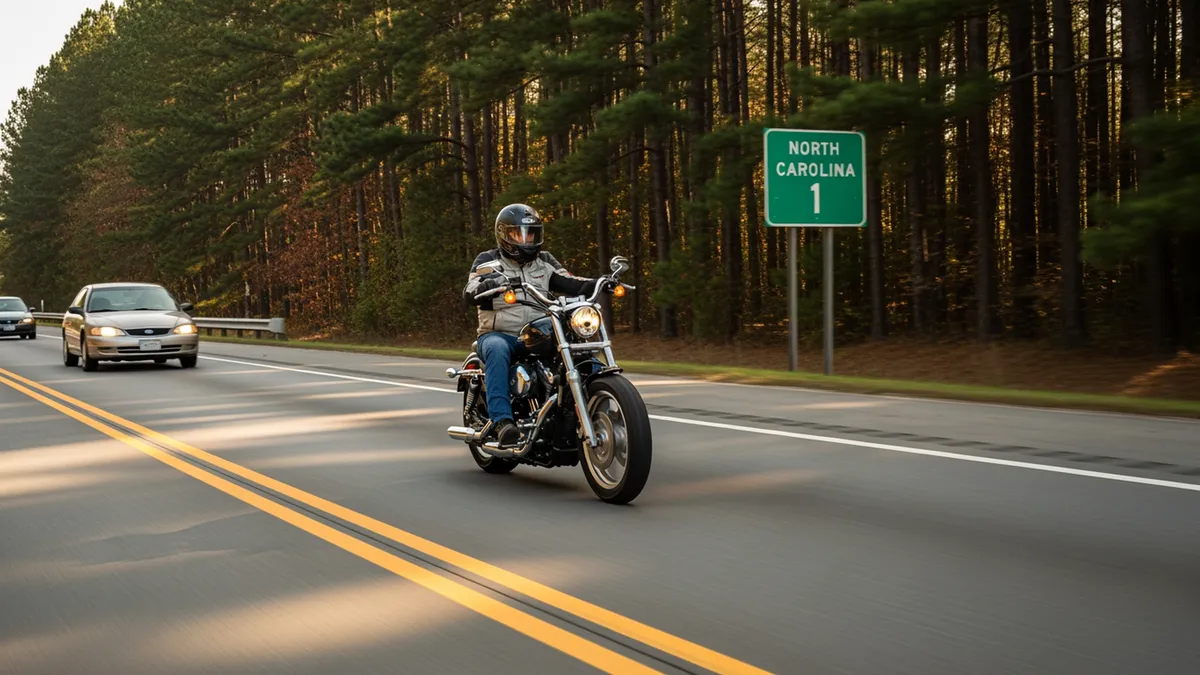
You did everything right. You watched your mirrors and held your lane, and a driver on US-1 still pulled across and put you on the pavement. Then comes the gut punch that turns a bad day into a crisis: the driver who hit you has no insurance. No policy to file against, no coverage for your hospital bills, and a lot of talk about "making it right" that is worth exactly nothing.
Why This Happens So Often in the Triangle
North Carolina requires drivers to carry minimum liability coverage of 30/60/25, meaning 30,000 dollars for injury to one person, 60,000 dollars per crash, and 25,000 dollars for property damage. That is the law, and plenty of drivers ignore it anyway. Across the Raleigh metro a meaningful number of drivers carry no insurance at all. Some let a policy lapse, some never bought one, and some are driving a car that is not even theirs. When one of them clips a motorcycle on I-540 or a frontage stretch of Capital Boulevard, the rider ends up in the ambulance and the at-fault driver has nothing to offer. The legal right to be paid is real, but the other driver's ability to pay it is often zero, and closing that gap is the whole game.
Your Real Backstop: Uninsured Motorist Coverage
The single most important protection against an uninsured driver is coverage that rides with you. Uninsured motorist coverage, paired with underinsured motorist coverage as UM/UIM, sits on your own North Carolina auto policy and steps in when the at-fault driver cannot pay. North Carolina does not treat this as an optional extra the way many states do. UM coverage is required on every auto policy written in the state, so if you have a policy, you almost certainly have this protection. It is still worth checking today: pull your declarations page and look for your UM and UIM limits, because on a motorcycle this coverage is the difference between a covered claim and a financial hole.
- ✓ Full medical documentation. Records that tie your injuries directly to the crash are the backbone of the claim.
- ✓ Proof the other driver was at fault. Your carrier only pays if the other driver was legally responsible, and in North Carolina any hint of rider fault is dangerous.
- ✓ Proof the other driver was uninsured. That is the trigger the entire UM claim depends on.
- ✓ A complete picture of your damages. Include future treatment and lost earning capacity, not just the bills already in hand.
- ✓ Careful handling of your own insurer. Open the UM claim, but do not give a recorded statement or sign a broad medical release.
Your Own Insurer Is Not Automatically on Your Side
Here is what blindsides riders. A UM claim is filed against your own insurance company, and that company does not simply hand over the money. It investigates, questions your injuries, and disputes how much you are owed. The friendly brand from the commercials can behave a lot like the other driver's insurer once real dollars are on the table. Fault matters even more here than in most states. North Carolina follows pure contributory negligence, so if your carrier can pin even 1 percent of the blame on you, your recovery can vanish completely, and because your own insurer stands in the shoes of the uninsured driver, it has every incentive to raise the same blame-the-rider arguments. That is why the scene evidence, the crash report, and the witness accounts still matter enormously, and why the general three-year deadline to file suit is a reason to act early rather than wait quietly. An experienced Triangle motorcycle attorney levels that field by proving the other driver's fault, confirming and applying the coverage that fits, and holding your carrier to the protection the law required it to sell you.
Ben Cochran and the Raleigh-Durham motorcycle accident attorneys at Hardison & Cochran represent riders hurt by negligent drivers. If you have questions after a crash, their team is here to help.